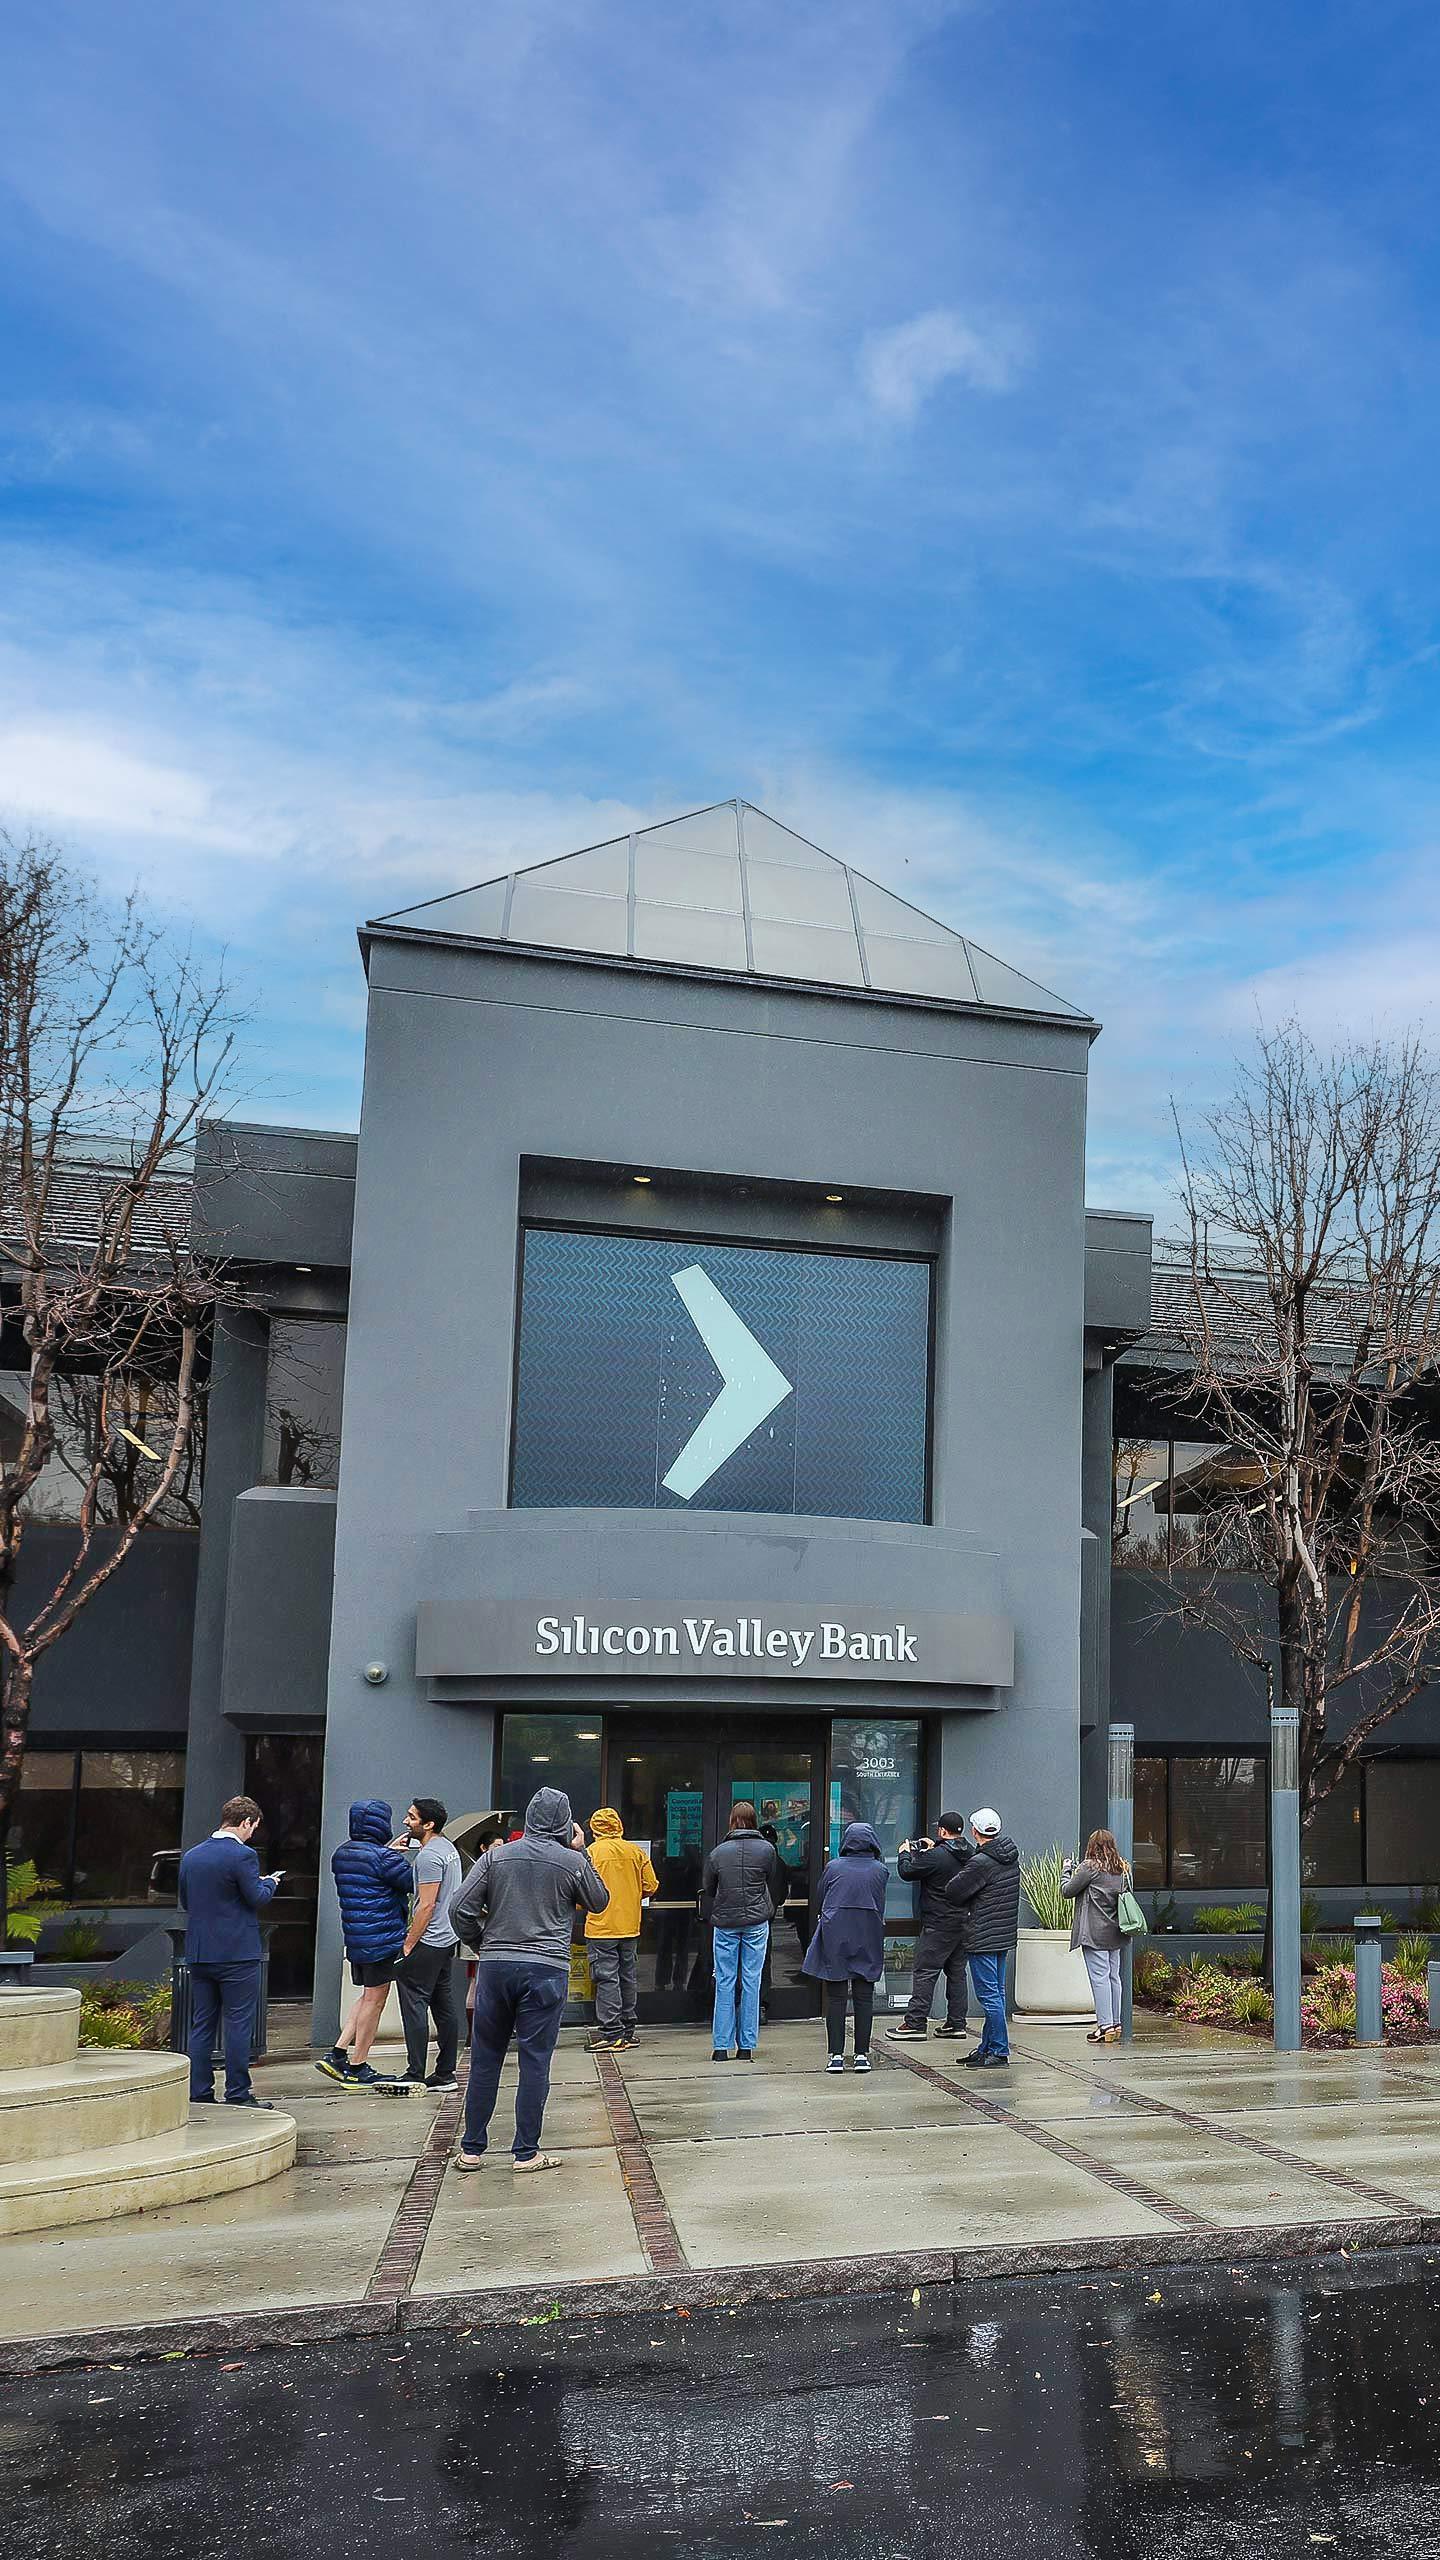
Federal Reserve Staff Knew of Silicon Valley Bank Risks as Early as March 2022, Review Finds
What's Happening?
A new independent review has revealed that Federal Reserve supervisory staff were aware of vulnerabilities at Silicon Valley Bank (SVB) as early as March 2022, but failed to take decisive action to mitigate
these risks. Michelle Bowman, the Fed's Vice Chair for Supervision, announced these initial findings, which suggest that poor management and a lack of prompt action by supervisory staff contributed to SVB's collapse in early 2023. This failure subsequently led to the failures of First Republic Bank and Signature Bank. The review, conducted by the Starling Advisory Group, identified a 'confluence of vulnerabilities' at SVB, including unrealized losses from rising interest rates and a heavy reliance on uninsured deposits from venture capital-backed tech firms. It also highlighted a 'long-standing culture of risk aversion' among staff and confusion over decision-making authority as factors contributing to the delayed response. The report clarified that a 2018 law loosening parts of the Dodd-Frank Act was not responsible for the supervisory delays.
Why It's Important?
The findings of this review are critically important for the U.S. financial system and its regulatory framework. The collapse of SVB, followed by First Republic Bank and Signature Bank, necessitated significant government intervention and shook public confidence in bank supervision. This report underscores the need for more proactive and decisive regulatory oversight to prevent future banking crises. The identified 'culture of risk aversion' and 'confusion over decision rights' within the Federal Reserve's supervisory process point to systemic issues that could undermine financial stability if not addressed. The implications extend to how banks manage interest rate risks and deposit concentrations, especially in specialized sectors. For the broader economy, such failures can lead to credit tightening, investor uncertainty, and potential ripple effects across various industries, particularly those reliant on venture capital funding. Ensuring robust and effective supervision is crucial for maintaining trust in the banking sector and safeguarding the economic well-being of the nation.
What's Next?
In response to the findings, the Federal Reserve is expected to implement reforms to its supervisory processes. Vice Chair Bowman has already indicated that the Fed has issued a Statement of Supervisory Operating Principles to refocus its supervision, emphasizing early identification of threats and prompt, decisive action. Future steps will likely involve clarifying decision-making authorities, addressing the culture of risk aversion, and enhancing the tools and support available to supervisory staff. There may also be discussions about potential legislative changes to strengthen banking regulations, although the review explicitly stated that the 2018 regulatory tailoring mandate was not a cause of the delays. Stakeholders, including other financial institutions, will be closely watching these reforms, as they could influence compliance requirements, risk management practices, and the overall regulatory environment for banks in the U.S. The goal is to learn from past mistakes to prevent similar failures and ensure the resilience of the financial system.
Beyond the Headlines
Beyond the immediate regulatory and financial implications, this review touches upon deeper issues of institutional accountability and organizational culture within critical government bodies. The revelation of a 'long-standing culture of risk aversion' and 'confusion over decision rights' suggests that bureaucratic inertia and a lack of clear leadership can have profound consequences, even in highly regulated sectors like banking. This raises questions about how such cultures develop and persist, and what mechanisms are needed to foster a more proactive and accountable environment. The report also implicitly highlights the tension between regulatory flexibility and stringent oversight, especially in a rapidly evolving financial landscape. The public's trust in financial institutions and their regulators is paramount, and the perceived failure of oversight can erode this trust, potentially leading to broader societal skepticism towards governmental effectiveness. Addressing these underlying cultural and structural issues will be crucial for long-term stability and public confidence.