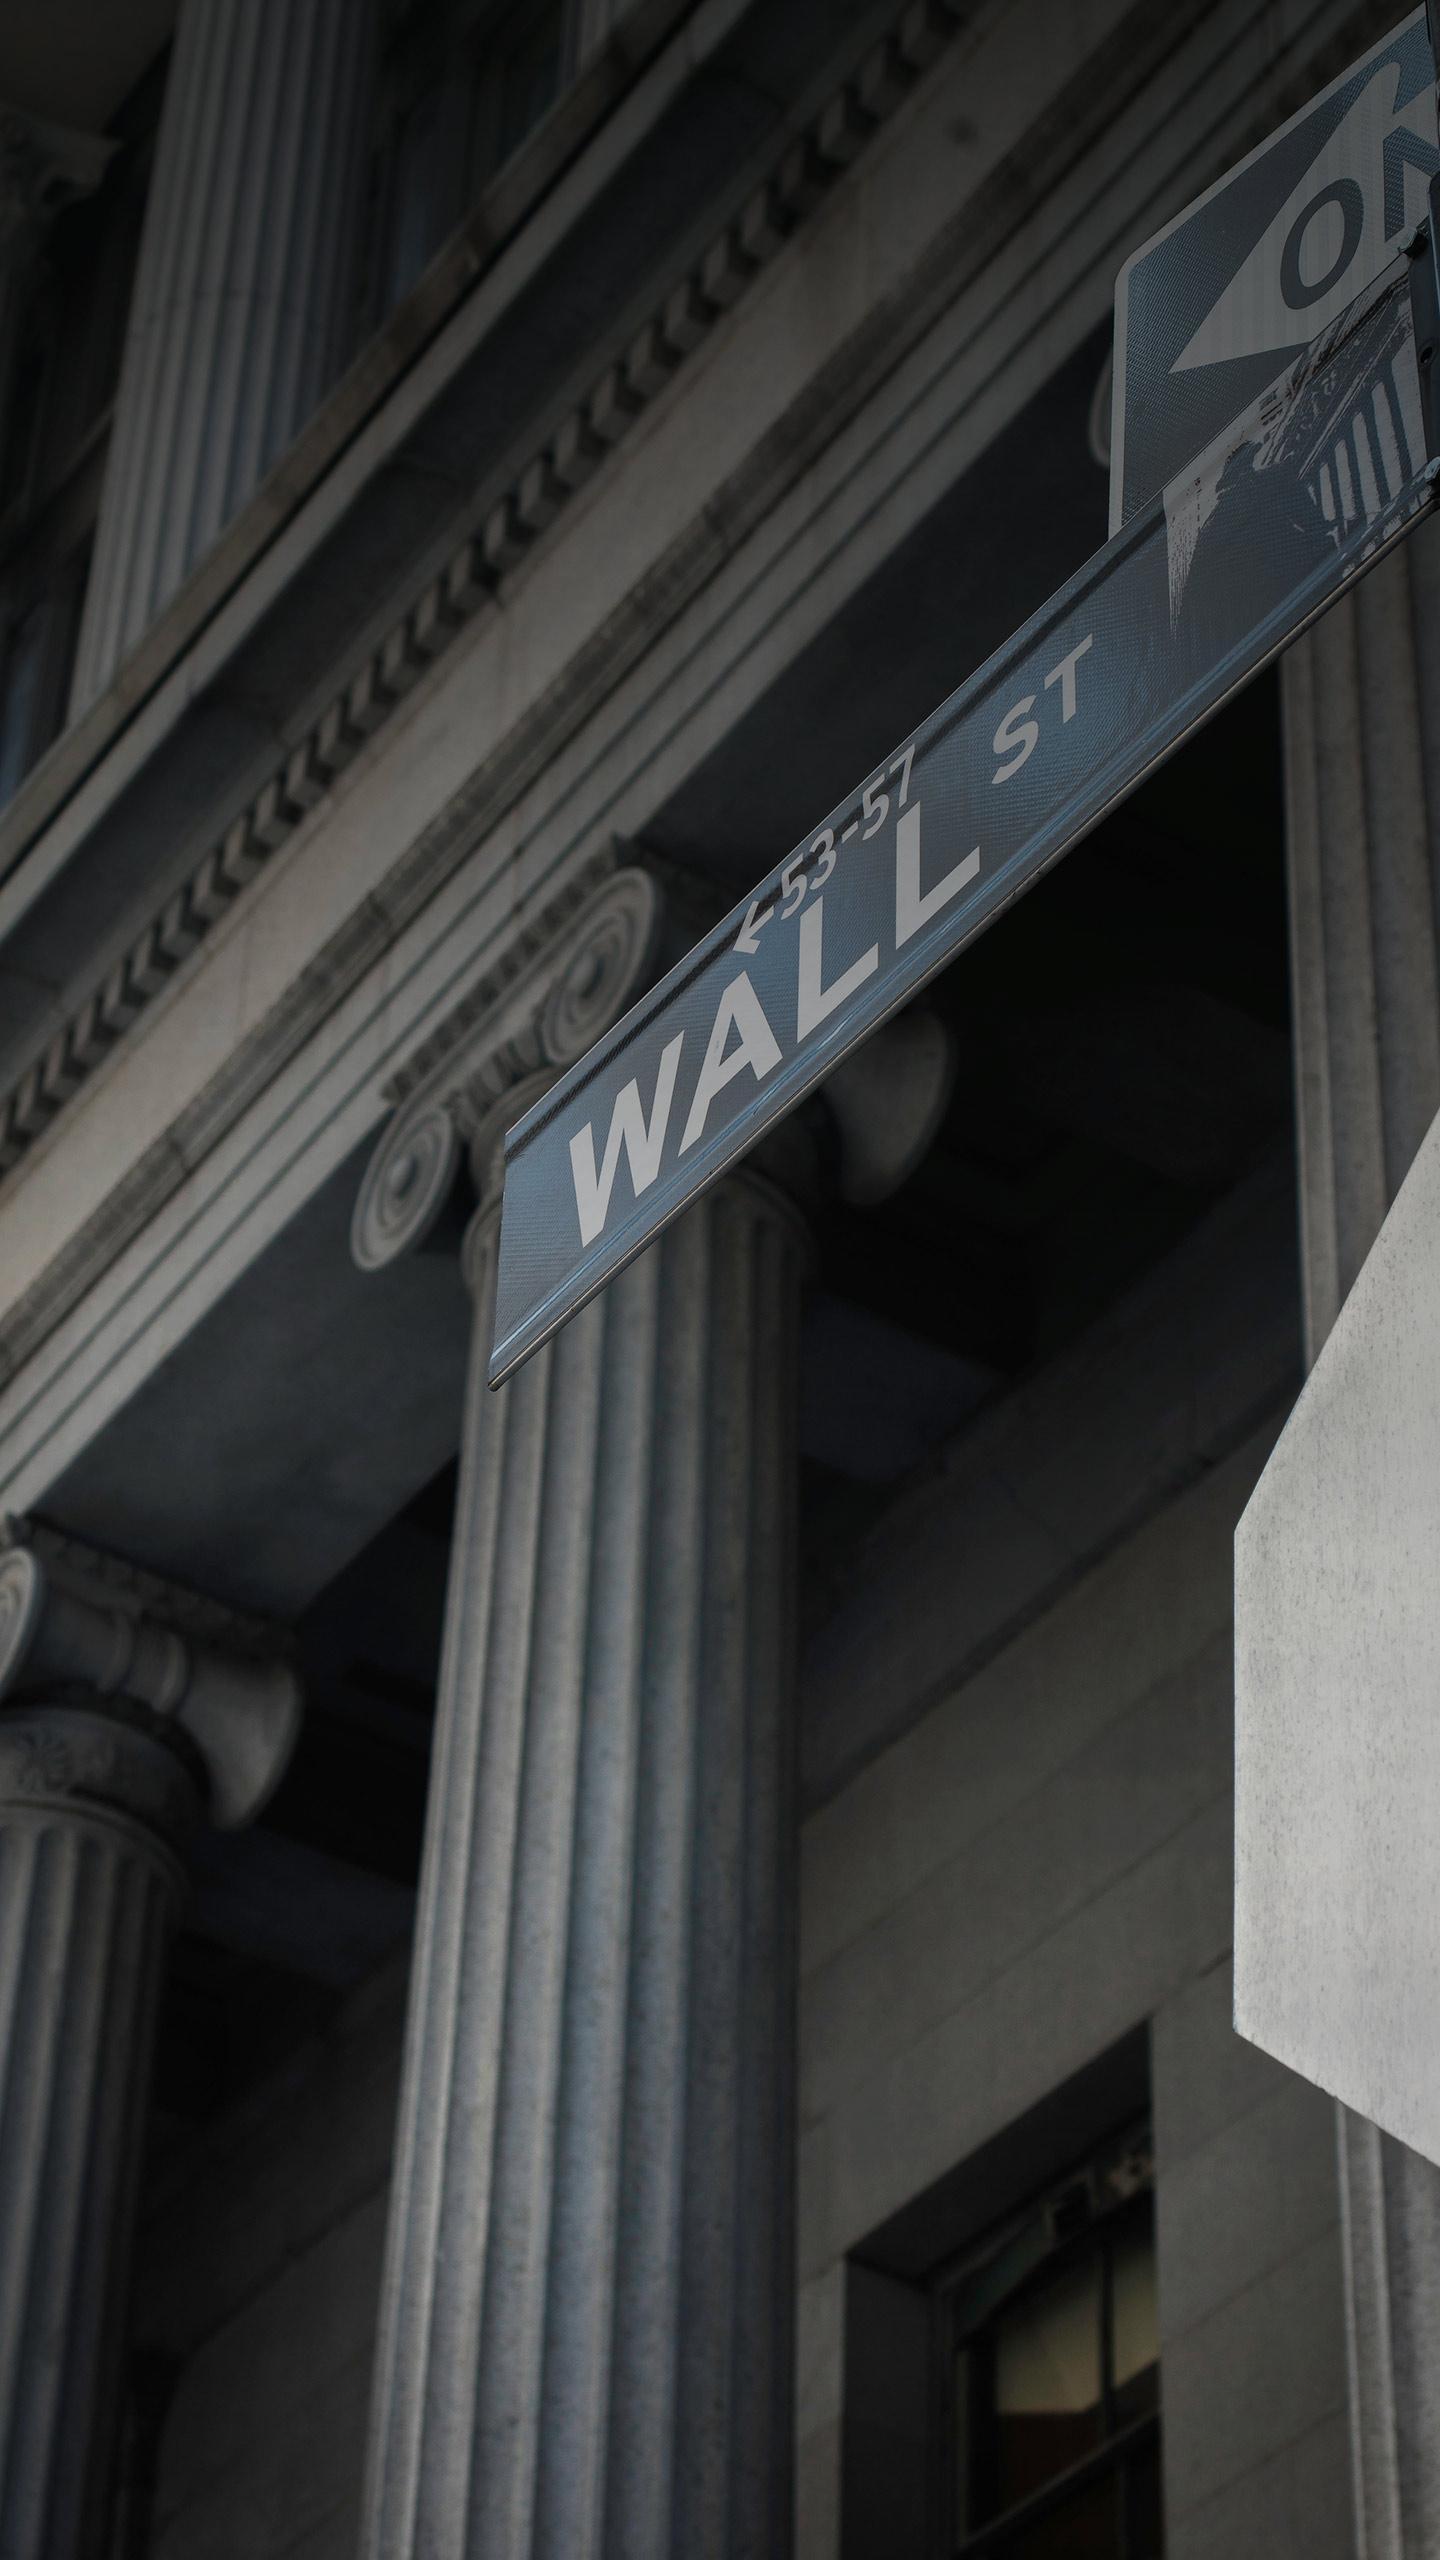
Wall Street Indexes Plummet as Tech and Chip Stocks Lead Broad Sell-Off
What's Happening?
Wall Street experienced a significant downturn on November 5, 2026, with major indexes recording their largest declines since last year's tariff-fueled sell-off. The Nasdaq Composite plunged 5.5%, entering
correction territory and marking its worst day since March 2020. The S&P 500 fell 4.4%, and the Dow Jones Industrial Average dropped 3.4%, shedding 1,830 points and erasing the previous day's post-election gains. The PHLX Semiconductor Index saw a 12.25% decline, its second-worst day on record, while the Nasdaq-100 index also suffered its sharpest fall since March 2020, dropping 6.4%. This broad sell-off was primarily driven by faltering tech heavyweights, a rout in chip stocks, and other companies that had benefited from the AI spending spree. The Cboe Volatility Index (VIX), often referred to as Wall Street's 'fear gauge,' surged approximately 70% to close at 28.18, its highest finish since March 30, indicating increased investor anxiety.
Why It's Important?
The sharp decline in U.S. stock markets, particularly in the technology and semiconductor sectors, signals a significant shift in investor sentiment following the midterm elections. The sell-off wiped out substantial gains from the previous day, which had been fueled by a decisive victory by Democrats. This reversal suggests that investors are now pricing in potential headwinds for the tech sector, especially concerning the pace of AI development. Concerns are emerging that Democratic control in Congress and gubernatorial wins in key states like Texas and Georgia could slow data-center permitting and power approvals, impacting the buildout of AI infrastructure. Companies heavily invested in AI, such as Nvidia, Advanced Micro Devices, and various memory chip manufacturers, experienced substantial losses. This market reaction indicates a re-evaluation of growth prospects for these sectors under the new political landscape, potentially leading to a more cautious investment environment for technology and AI-related industries.
What's Next?
The immediate aftermath of this market downturn will likely involve continued volatility as investors assess the implications of the midterm election results on various sectors. The Cboe Volatility Index (VIX) closing at a high level suggests that market uncertainty is expected to persist in the short term. Analysts like Adam Turnquist, chief cross-asset strategist at LPL Financial, note that while volatility is high, it has not yet reached 'capitulation or contrarian extremes' that typically mark market bottoms, implying further potential for market fluctuations. Companies like Airbnb and Cloudflare are scheduled to release third-quarter earnings, which could provide further insights into specific sector performance and investor sentiment. The performance of AI-related ETFs and individual chip stocks will be closely watched as investors try to determine the next phase of the tech trade, particularly concerning how potential regulatory or permitting changes might affect their growth trajectories.
Beyond the Headlines
This market correction extends beyond immediate financial losses, hinting at deeper shifts in the investment landscape and the perceived risks associated with rapid technological expansion. The significant drop in AI-related stocks, despite strong underlying technological advancements, suggests that political and regulatory environments are increasingly influential factors in market valuations. The 'Blue Wave' election outcome appears to be prompting a re-evaluation of the unchecked growth assumptions that have driven the AI boom. This could lead to increased scrutiny on data center expansion, energy consumption, and the broader societal impact of AI, potentially ushering in a period where sustainability and regulatory compliance become as critical as innovation for tech companies. The market's reaction underscores the interconnectedness of political outcomes, economic policy, and technological development, signaling a potential recalibration of investor expectations for high-growth sectors.