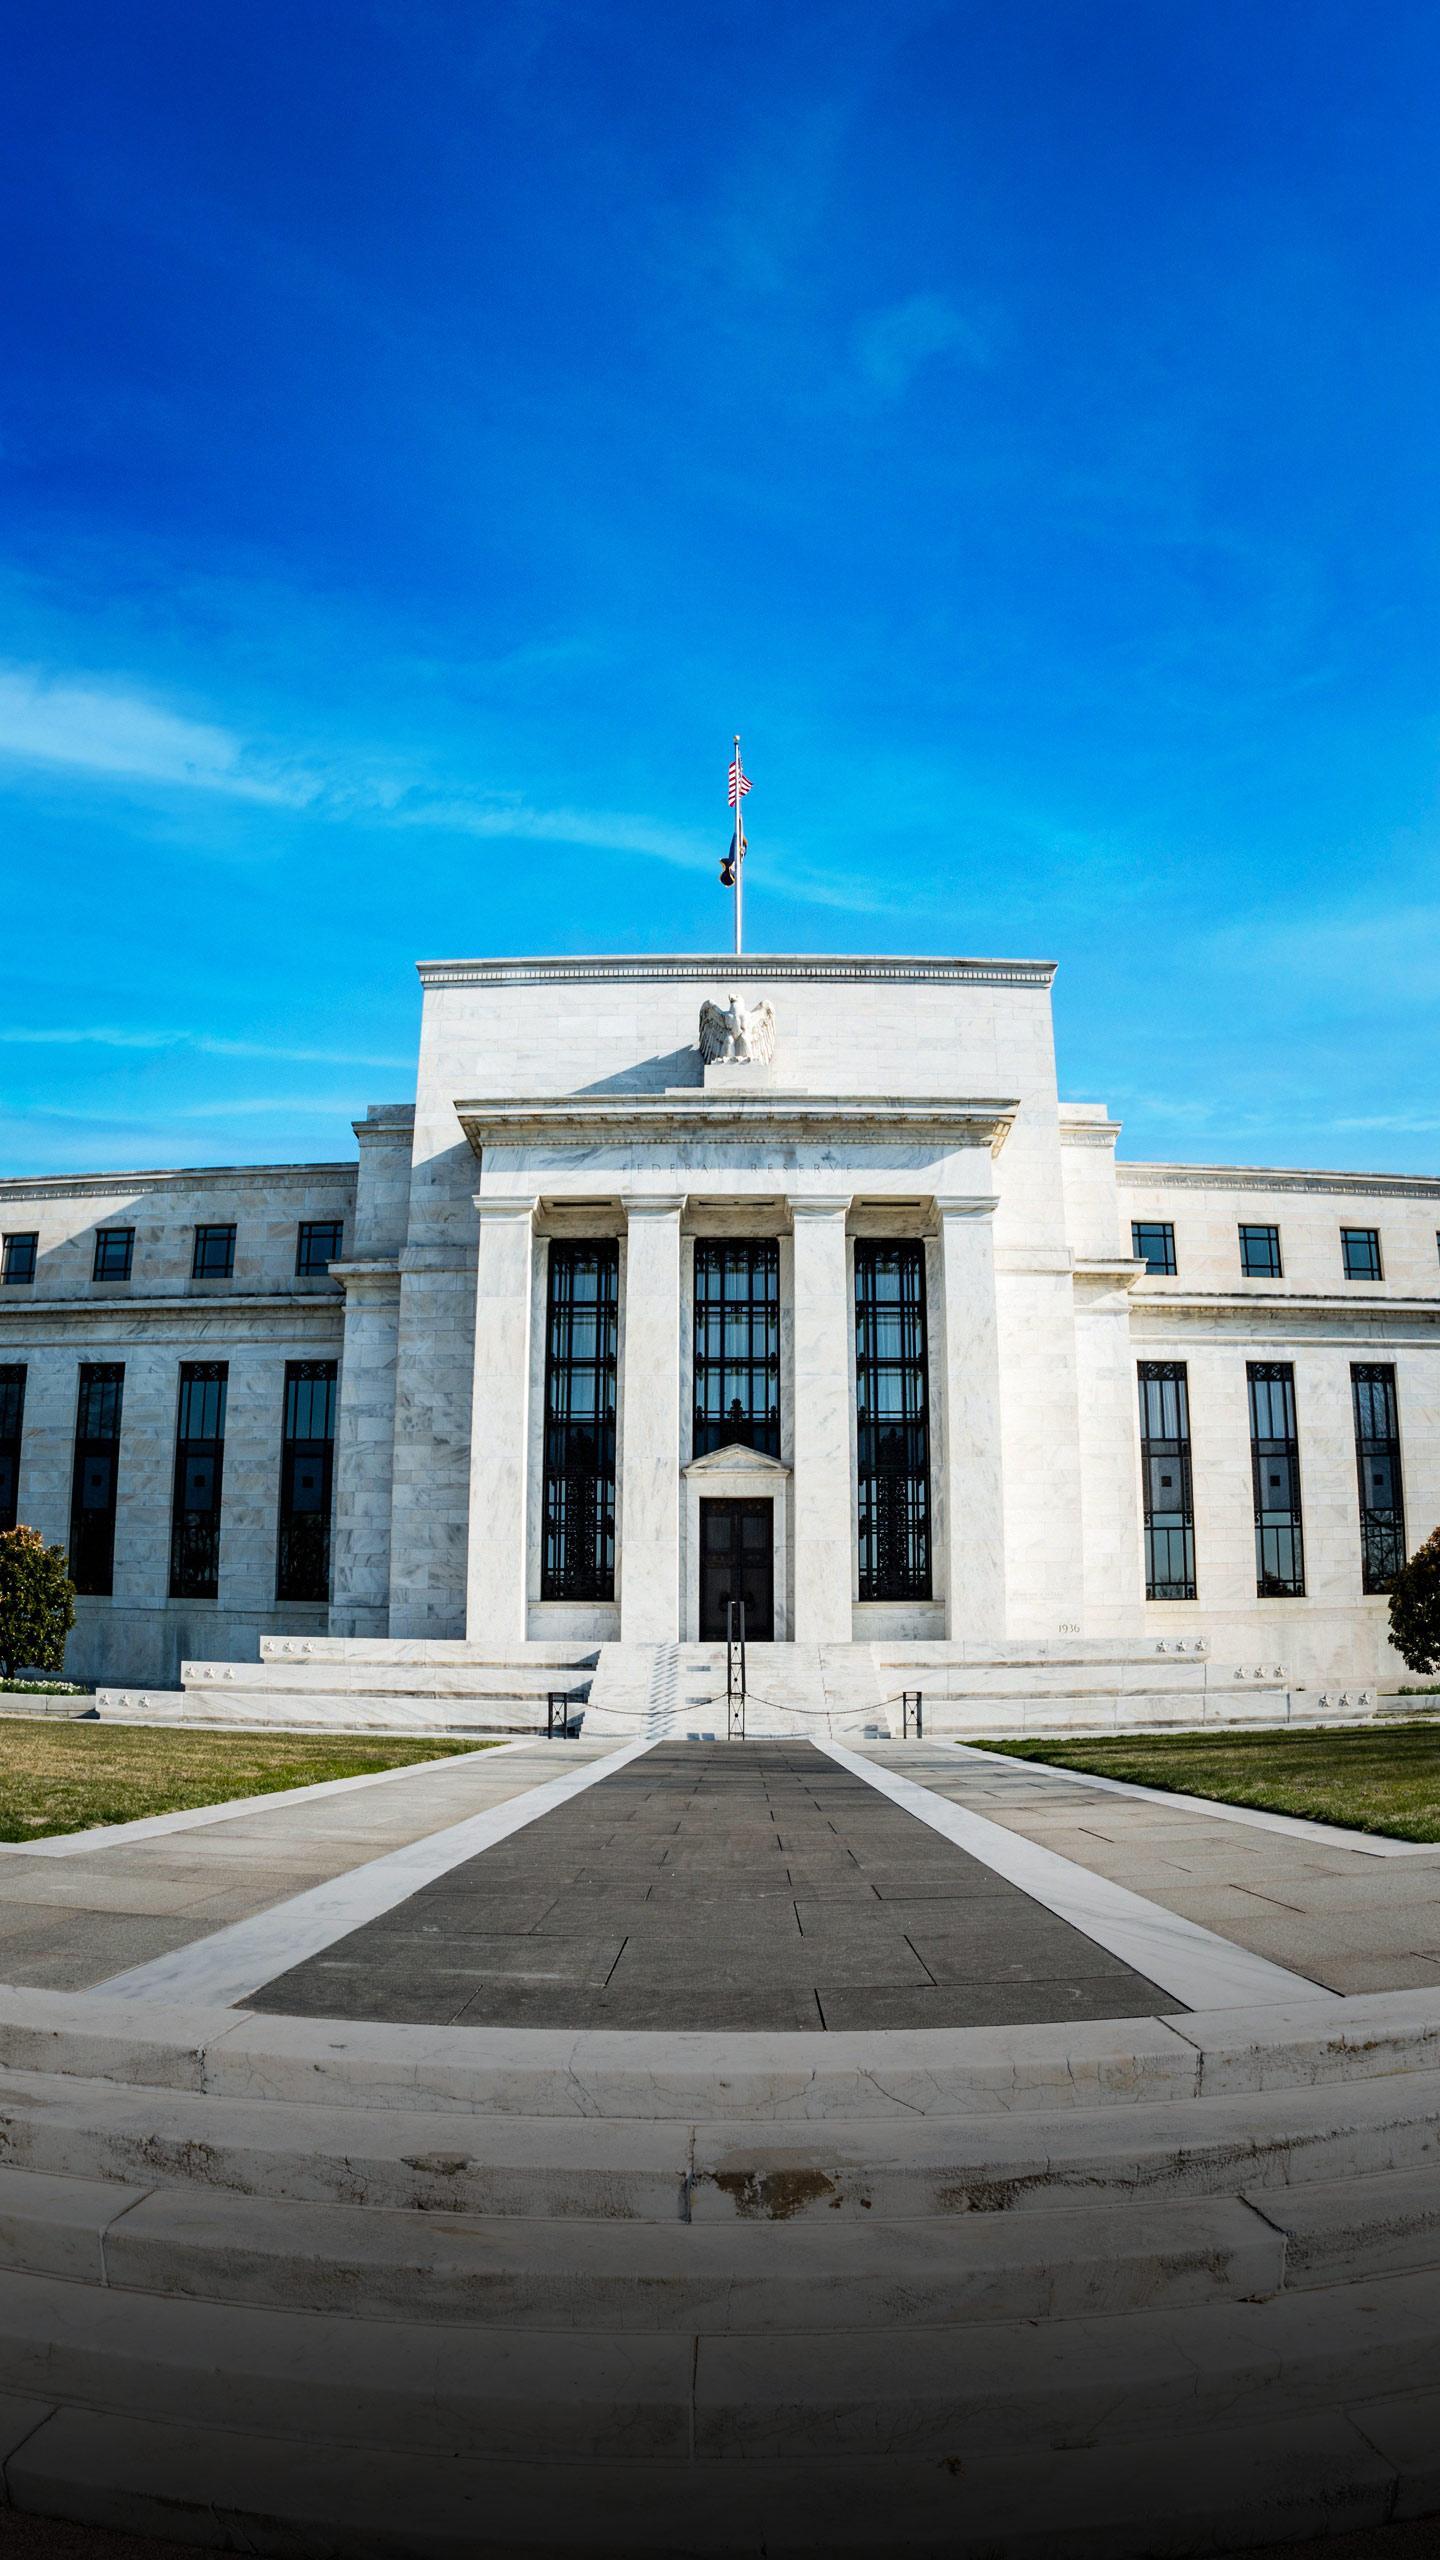
Federal Reserve Vice Chair Bowman Announces Supervision Restructuring and Regulatory Tailoring Updates
What's Happening?
Federal Reserve Vice Chair for Supervision Michelle Bowman has announced a significant restructuring of the Fed’s supervision function and previewed updates to the regulatory tailoring framework. Bowman stated
that the Fed's examinations had become overly focused on process and checklists, rather than evaluating safety and soundness with judgment and expertise. The new approach will refocus supervision on material risks to a bank's financial viability. The restructuring includes realigning the supervision function to foster accountability and clear decision-making, addressing a 'mismatch between authority for decisionmaking and accountability' highlighted in the Starling review of Silicon Valley Bank's failure. The new structure will feature five regions, each led by a regional leader overseeing supervisory activity and reporting to the Board’s Deputy Director of Supervision. Additionally, the Board will consider broader structural reforms to bank portfolios based on asset size and updates to the large bank tailoring framework, including increasing static dollar thresholds for inflation and economic growth.
Why It's Important?
This overhaul of the Federal Reserve's supervision framework is critical for the stability and efficiency of the U.S. banking system. By shifting focus from process to substantive risk, the Fed aims to prevent future bank failures and ensure financial institutions are more resilient. The restructuring addresses long-standing issues of accountability and decision-making within the Fed's supervisory divisions, which were exposed by recent banking crises. For U.S. industries, particularly the financial sector, these changes mean a more targeted and potentially more effective regulatory environment. Banks will need to adapt to clearer, risk-calibrated supervision, which could influence their operational strategies and risk management practices. The updates to the regulatory tailoring framework, including increased asset thresholds, will also impact how different sizes of banks are regulated, potentially easing burdens on smaller institutions while maintaining robust oversight for larger ones, thereby affecting their competitive landscape and compliance costs.
What's Next?
The Federal Reserve Board is expected to consider broader structural reforms to bank portfolios and updates to the large bank tailoring framework later this year. This will include proposals to increase static dollar thresholds in regulations to account for inflation and economic growth, with a mechanism for updating these thresholds every five years. The Fed also plans to expand the range of institutions treated as community banks, aiming to apply appropriately tailored supervision. Banks and financial institutions will need to closely monitor these forthcoming proposals to understand their new compliance obligations and strategic implications. The implementation of the new regional supervisory structure will also be a key area to watch, as it aims to improve accountability and decision-making efficiency within the Fed's supervisory functions. Stakeholders will likely engage in public comment periods for these proposed changes, influencing the final regulatory landscape.
Beyond the Headlines
The Federal Reserve's supervisory revamp signals a deeper re-evaluation of regulatory philosophy in the wake of recent financial instability. The move away from 'checklist' supervision towards a more judgment-based, risk-focused approach reflects an acknowledgment that rigid compliance can sometimes obscure underlying systemic risks. This shift has ethical implications, as it places greater emphasis on the expertise and discretion of supervisors, requiring a high degree of integrity and sound judgment to avoid regulatory capture or arbitrary enforcement. Legally, the changes aim to clarify supervisory expectations and align responsibility with accountability, potentially reducing legal challenges related to regulatory actions. Culturally, it could foster a more proactive and adaptive regulatory environment within the Fed, encouraging continuous learning and responsiveness to evolving financial risks. In the long term, this could lead to a more resilient and dynamic U.S. financial system, better equipped to handle unforeseen economic challenges.