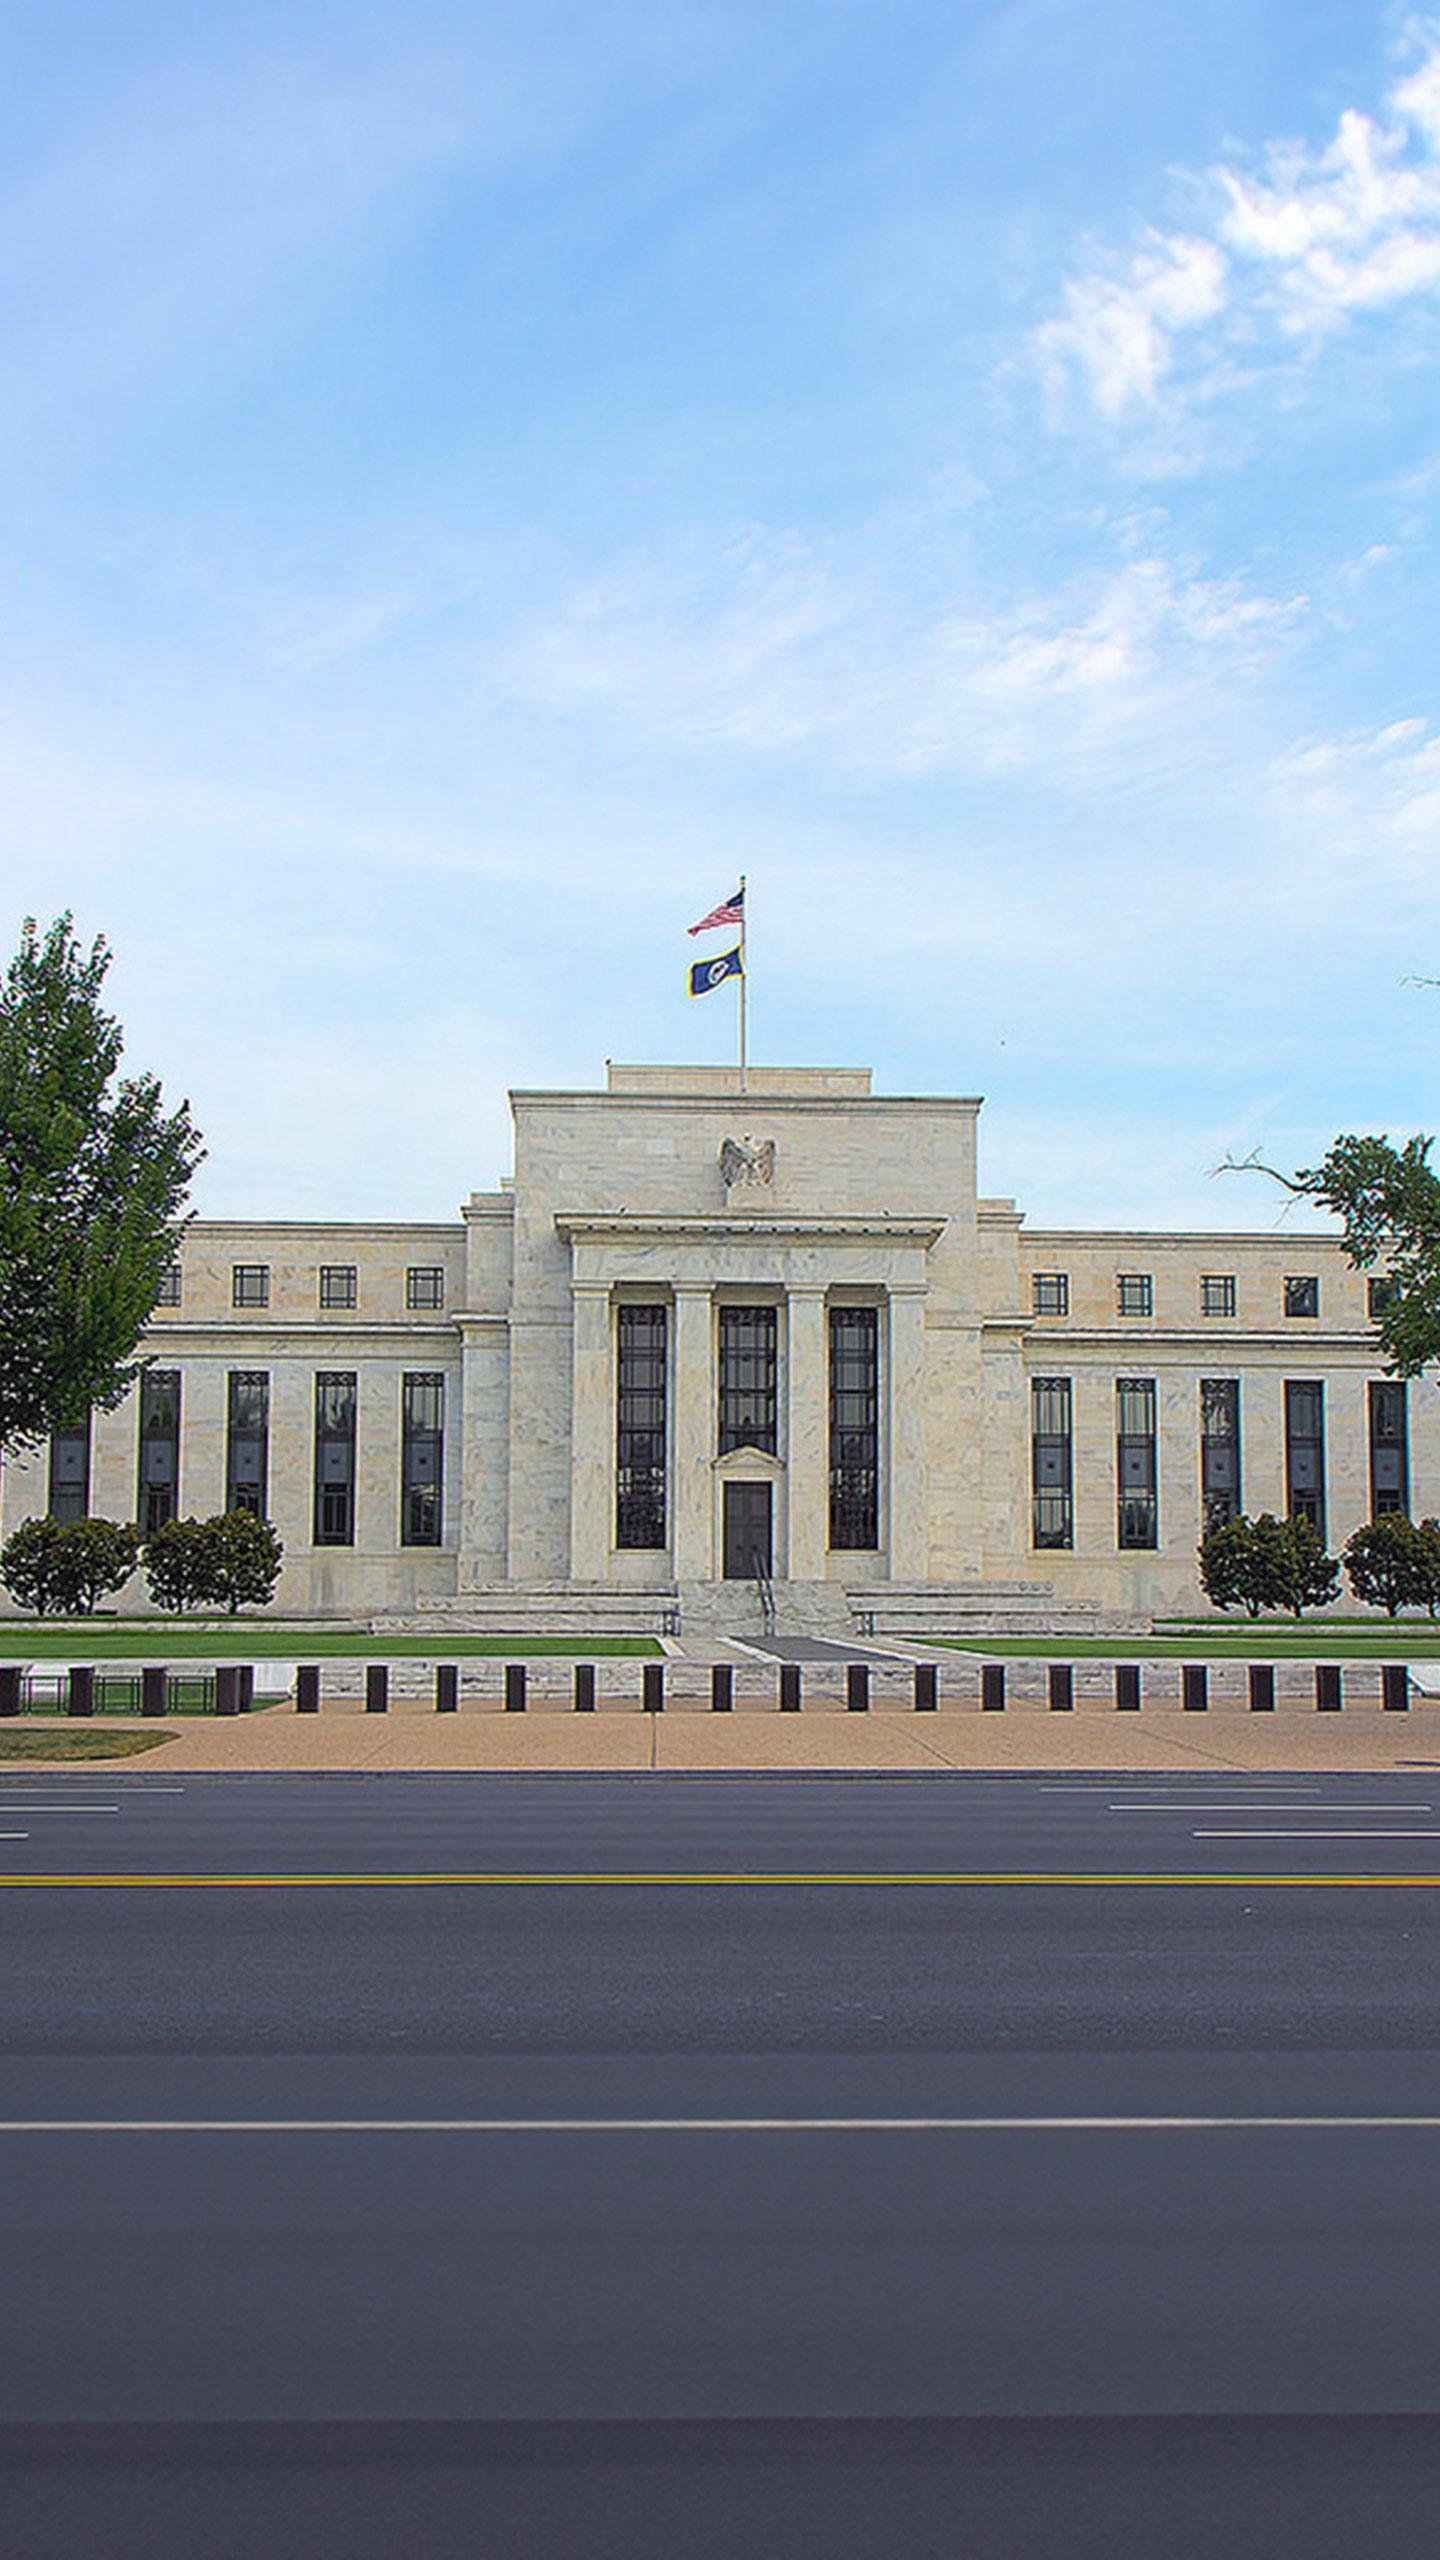
U.S. Jobs Reports to Influence Federal Reserve Rate Decisions and Global Markets
What's Happening?
The U.S. labor market is under intense scrutiny as several key employment reports are scheduled for release in early November 2026, including the Job Openings and Labor Turnover Survey (JOLTS) on November 3
and the comprehensive Employment Situation report on November 6. These reports, which cover job openings, hires, quits, layoffs, nonfarm payroll employment, hours, earnings, unemployment, and labor-force participation, are critical for assessing the health of the U.S. economy. The Federal Reserve held its key rate at 3.75%–4.00% on October 28, 2026, with two members voting for a quarter-point increase. Strong employment data, particularly robust payroll growth, rising wages, and falling unemployment, could signal persistent demand and elevated inflation, potentially leading the Federal Reserve to maintain or even increase interest rates. Conversely, a weak report could strengthen expectations for Fed easing.
Why It's Important?
U.S. employment data significantly influence Federal Reserve rate expectations, which in turn affect Treasury yields, the dollar's strength, and global capital flows. A strong jobs report, indicating a robust labor market, could lead to higher U.S. interest rates and a stronger dollar, making U.S. assets more attractive and potentially drawing capital away from emerging markets like Mexico and Brazil. This can cause currency fluctuations, such as the recent weakening of the Mexican peso against the dollar. For U.S. investors, this means potential currency swings in their Latin American assets. For U.S. businesses with international supply chains, a strong U.S. labor market supports demand for exports and sustains remittance flows, but a stronger dollar can make peso-denominated costs cheaper. The data also provides insights into whether labor demand is cooling or if workers remain confident in the job market.
What's Next?
Investors will closely monitor the upcoming jobs reports for surprises relative to consensus, focusing on average hourly earnings, payroll revisions, JOLTS data, and continuing claims to gauge the breadth of hiring and labor supply changes. The two-year Treasury yield and the dollar will serve as immediate indicators of Fed repricing, while the peso-dollar and real-dollar exchange rates will reflect impacts on Latin American markets. The Federal Reserve's next meeting is scheduled for December 8–9, 2026, and the jobs data will be a key input into its decision-making process regarding future interest rate adjustments. A strong report could reinforce the Fed's cautious stance on inflation, while a weak report might prompt discussions about easing monetary policy. The market's interpretation of these reports will determine immediate shifts in currency values and bond yields, impacting investment strategies globally.
Beyond the Headlines
The intricate relationship between U.S. labor market data and global financial stability extends beyond immediate market reactions. The Federal Reserve's decisions, heavily influenced by employment figures, have ripple effects on international trade, investment, and economic development, particularly in countries with strong economic ties to the U.S. The concept of 'Fed repricing' highlights how quickly market expectations can shift based on new data, underscoring the interconnectedness of global financial systems. Furthermore, the impact on remittances to countries like Mexico and Central America reveals a direct human element, as the employment conditions of Mexican workers in the U.S. directly affect the purchasing power of families back home. This dynamic illustrates how U.S. domestic economic policies, driven by labor market performance, can have significant social and economic consequences far beyond its borders, influencing household incomes and regional economies in Latin America.